
Quick Answer
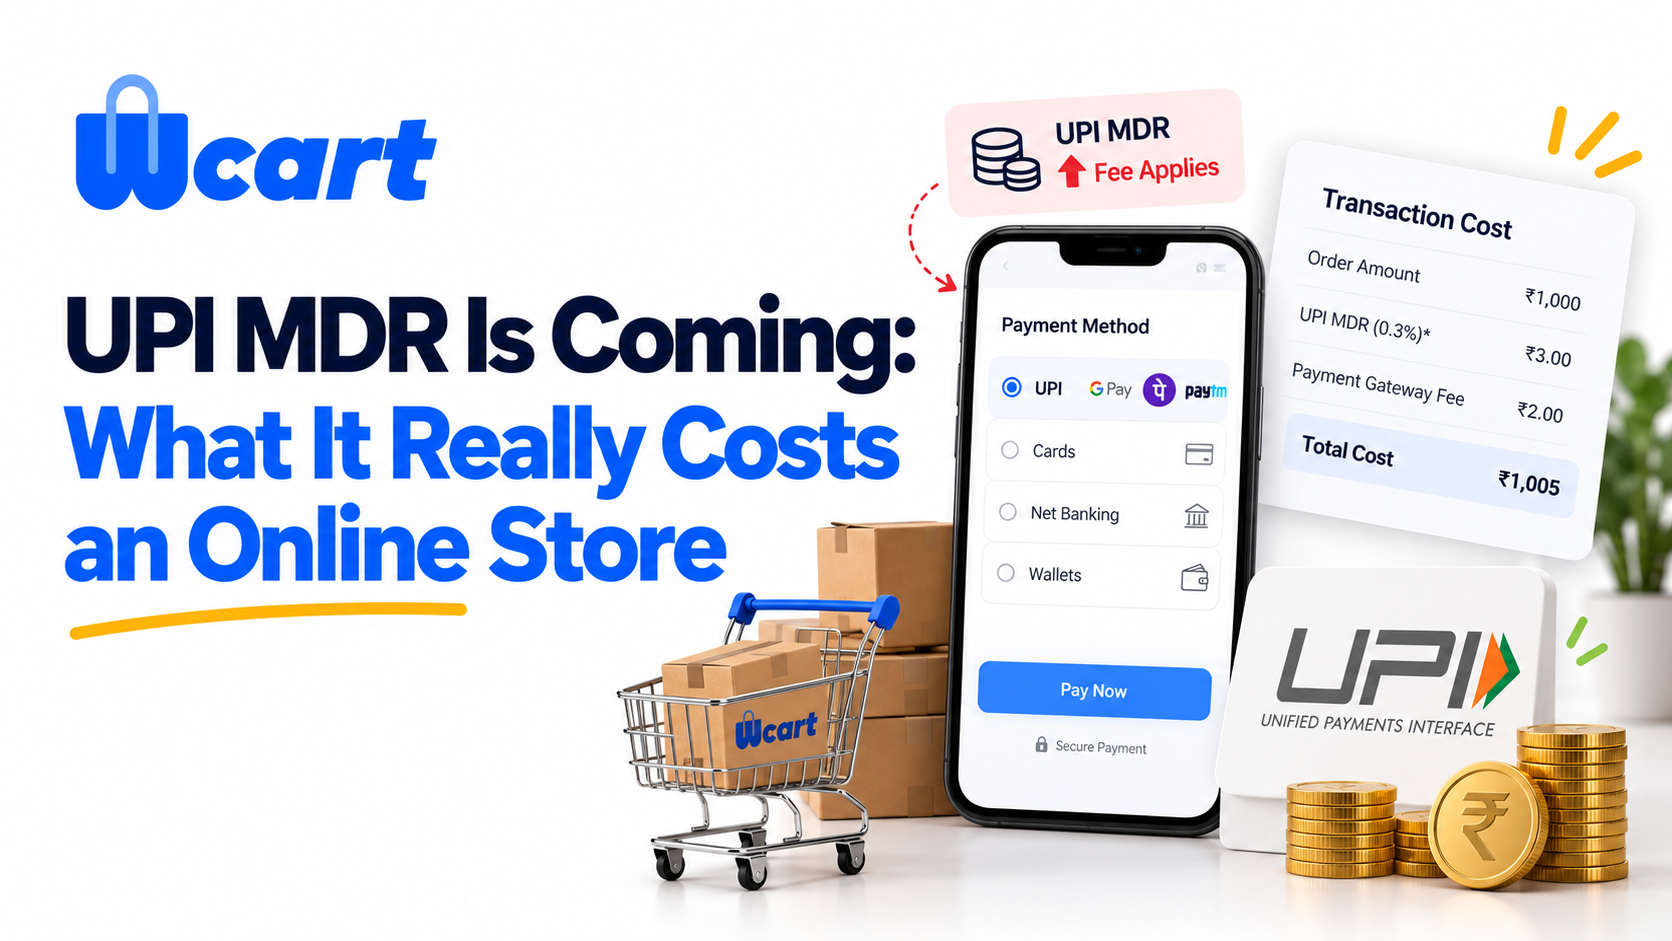
India is ending six years of free merchant UPI — but only for bigger tickets. Under the framework announced on 15 September 2026, a 0.4% merchant discount rate (MDR) applies to regular person-to-merchant (P2M) UPI payments above ₹2,000, with the fee capped at ₹300 once a payment reaches ₹75,000. Shoppers pay nothing extra; the cost sits with the merchant.
For most small online stores, the real-world hit is smaller than the headlines suggest. A store whose average UPI order is ₹1,500 pays nothing. A store selling ₹5,000 jackets pays ₹20 per UPI order. The question that matters isn’t “Is UPI paid now?” — it’s “What share of my UPI revenue sits above ₹2,000, and which merchant category am I in?”
This guide answers both, with numbers.
Where the rollout date stands (12 October 2026)
The original effective date is 15 October 2026. Since then, multiple outlets have reported that NPCI’s UPI Steering Committee is weighing a deferral to 1 January 2027, so that the fee doesn’t land in the middle of festive-season sales. Reports also say the committee is considering an exemption for businesses with annual turnover up to ₹40 lakh.
Neither change had been officially announced at the time of writing. Treat 15 October as live until NPCI or your payment provider tells you otherwise in writing — and use any extra time to get the prep work below done.
The rate card, decoded
| Payment type | What the merchant pays |
| Person-to-person (P2P) transfer | Nothing |
| Any merchant payment of ₹2,000 or less | Nothing |
| Standard merchant payment above ₹2,000 | 0.4% of the amount |
| Standard merchant payment of ₹75,000 or more | Flat cap of ₹300 |
| Railways, telecom, insurance, fuel, agricultural inputs (above ₹2,000) | Flat ₹5 per payment |
| Small merchants under the P2PM category (QR collections up to ₹1 lakh/month) | Nothing, at any ticket size |
Two details most explainers skip:
- The threshold is per payment, not per month. A ₹2,000 order is free; a ₹2,001 order is charged on the full amount (≈ ₹8), not just the ₹1 above the line.
- P2PM status isn’t permanent. As reported from NPCI’s framework, a small merchant whose UPI collections stay above ₹1 lakh for three consecutive months can be moved into the standard P2M category — and become liable for MDR. A good festive quarter can trigger this.
Is your online store even in scope?
Work through these three questions in order.
1. How do you collect UPI? If customers pay through a payment gateway or aggregator on your website, you are almost certainly a P2M merchant, not a P2PM small vendor. The small-merchant exemption was designed around QR collections into a merchant’s own account. Confirm your classification with your gateway — don’t assume it from your size.
2. What’s your UPI order-value mix? Pull last quarter’s UPI orders and split them at ₹2,000. Everything at or below the line stays free regardless of what else changes.
3. What do you sell? If you’re in one of the flat-₹5 categories (insurance, fuel, telecom and similar), your cost per high-value order is fixed and tiny. Most D2C and ecommerce categories — fashion, electronics, beauty, home — fall under the standard 0.4%.
What it actually costs: three store profiles
Per-order cost is simple: order value × 0.4% for UPI payments above ₹2,000, capped at ₹300.
| Order value | MDR |
| ₹1,999 | ₹0 |
| ₹2,500 | ₹10 |
| ₹4,500 | ₹18 |
| ₹12,000 | ₹48 |
| ₹50,000 | ₹200 |
| ₹1,00,000 | ₹300 (cap) |
The per-order number is less useful than your blended rate across all UPI revenue. Here’s how three typical stores compare (illustrative figures):
Store A — Snacks & daily essentials. 800 UPI orders/month, average ₹650, almost nothing above ₹2,000. → Monthly MDR: ≈ ₹0. No action needed beyond monitoring.
Store B — Ethnic wear. 300 UPI orders/month. 180 orders average ₹900; 120 orders average ₹4,500. → MDR = 120 × ₹18 = ₹2,160/month on ₹7.02 lakh of UPI revenue — a blended rate of about 0.31%.
Store C — Consumer electronics. 150 UPI orders/month, average ₹18,000, all above ₹2,000. → MDR = 150 × ₹72 = ₹10,800/month — the full 0.4% on ₹27 lakh.
The takeaway: the higher your average order value, the closer your blended rate gets to 0.4%. Below that, the ₹2,000 threshold does a lot of the work for you.
MDR is not your whole payment bill
The 0.4% is a regulated ceiling on what the UPI ecosystem collects from merchants. It is not necessarily the same as what your payment gateway will deduct. Gateways have their own commercial terms, and some may restructure UPI pricing around the new framework.
Before you model margins, get these in writing from your provider:
- Your merchant category (P2PM or P2M) and the basis for it
- The exact UPI rate you’ll be charged above and below ₹2,000
- Whether any existing platform or gateway fee on UPI changes
- How MDR will appear on settlement reports
- The confirmed effective date for your account
Don’t add a “UPI fee” at checkout
The framework treats MDR as a merchant-side cost. Banks have been advised that merchants should not pass it to customers as a separate UPI charge, and a visible surcharge is also a fast way to lose a sale.
If payment costs genuinely squeeze a product line, handle it the normal way: review that product’s pricing as a whole, not the payment method. Customers accept a ₹20 higher price far more easily than a ₹18 “UPI fee” line in their cart.
Seven moves to make this month
- Split your UPI data at ₹2,000. Know your exposure in rupees, not percentages.
- Get your classification in writing. One email to your gateway settles whether any of this applies to you.
- Watch the ₹1 lakh line if you’re P2PM. Three strong months in a row can move you into the paid category.
- Rebuild your margin sheet with a payment-cost column per product, using the blended rate for its typical order value.
- Update reconciliation. Settlement amounts on large UPI orders will no longer equal order value. Make sure your finance team can match them.
- Keep UPI front and centre at checkout. It’s still the payment method most Indian shoppers reach for first; burying it to save 0.4% usually costs more in abandoned carts.
- Set a calendar check for 1 January 2027. If the deferral is confirmed, that becomes your new go-live date — revisit your numbers then.
Where your storefront fits in
A 0.4% fee on large orders is manageable. What hurts margins far more is paying marketplace commissions on top of payment costs, or losing repeat buyers you never get to contact again.
With Wcart, you run your own branded online store, so you control the checkout, see your order data directly and build repeat business from your own customer list. That gives you room to absorb small payment-cost changes like this one — and the visibility to price for them properly.
Start building your store with Wcart →
FAQs
Do customers pay anything extra for UPI from 15 October? No. MDR is charged to the merchant. UPI stays free for people paying.
If an order is ₹2,500, is the fee charged on ₹500 or ₹2,500? On the full ₹2,500 — about ₹10 at 0.4%.
Will splitting a ₹4,000 order into two ₹2,000 payments avoid MDR? Don’t engineer checkout around this. It adds friction, may break your provider’s terms, and saves about ₹16. Price the product sensibly instead.
Is UPI AutoPay (subscriptions) affected? Reporting on NPCI’s FAQ indicates UPI mandates carry no prescribed MDR. If you sell subscriptions, confirm with your provider how recurring debits will be treated on your account.
Has the date been pushed to January 2027? As of 12 October 2026, a deferral to 1 January 2027 is widely reported as under consideration, but not officially confirmed. Check NPCI and your payment provider for the final word.
I sell on my own site and through Instagram DMs with a UPI QR. Am I treated differently on each? Possibly. Your QR collections and your gateway collections may sit under different merchant classifications. Ask your bank and gateway separately.
Bottom line
The new UPI MDR is narrow by design: free below ₹2,000, 0.4% above it, ₹300 at the top, nothing for genuinely small QR merchants. For most online stores, the impact is a fraction of a percent of revenue. Know your order-value split, confirm your category in writing, keep UPI easy to use — and spend your energy on the margin levers you actually control.





Leave a Reply